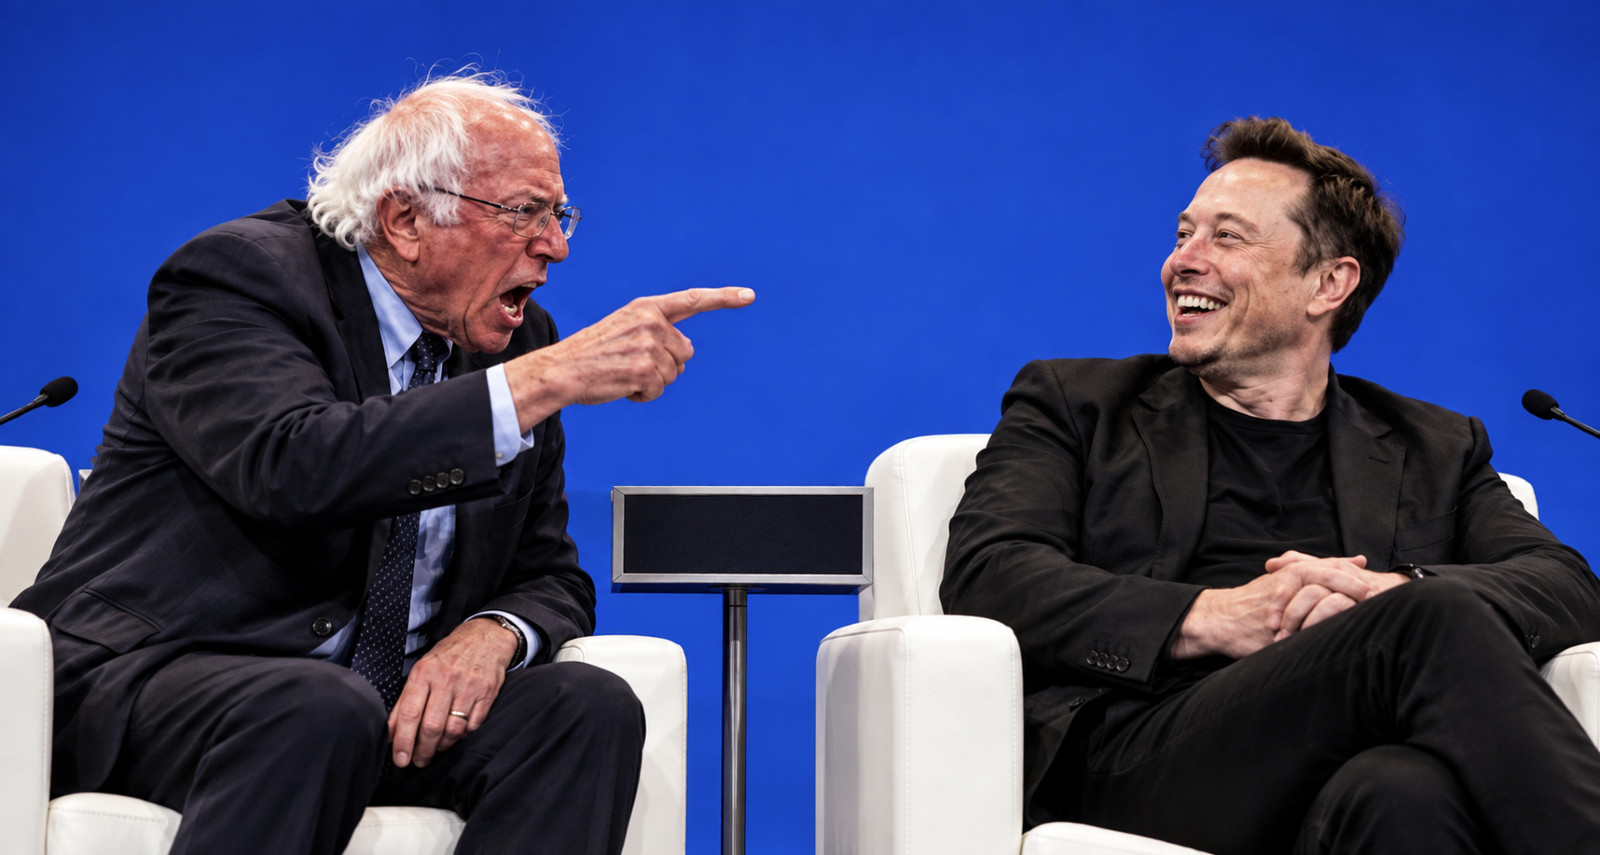
"BERNIE THREATENS ELON MUSK: The Massive Meltdown & Instant Regret!"
SpaceX’s Nasdaq-100 Entry Pulls Musk-Sanders Wealth Fight Into Americans’ Retirement Accounts
SpaceX’s record IPO and rapid addition to major stock indexes have given many retirement savers indirect exposure to Elon Musk’s company, even as a separate political fight over billionaire wealth and Bernie Sanders’ proposed AI sovereign wealth fund intensifies.
September 15, 2026
Millions of Americans may now have indirect exposure to SpaceX through index funds held in 401(k)s, IRAs and other retirement accounts after Elon Musk’s rocket and satellite company completed the largest initial public offering in history and was rapidly added to several major market benchmarks.
SpaceX began trading on Nasdaq under the ticker SPCX on June 12 after pricing 555,555,555 Class A shares at $135 each. The company later closed the offering with the underwriters’ full overallotment option exercised, bringing the total to 638,888,888 shares. At the offer price, those shares represented about $86.25 billion in gross proceeds; SpaceX reported roughly $85.7 billion after underwriting commissions and offering costs. Nasdaq has described the deal as the largest IPO in history.
The company’s path into passive investment portfolios was unusually fast. Nasdaq announced on June 26 that SpaceX would join the Nasdaq-100 before the market opened on July 7 under its new Fast Entry provisions. The Nasdaq-100 tracks 100 of the largest nonfinancial companies listed on Nasdaq and is followed by more than 200 investment products representing more than $800 billion in assets under management.
Invesco later confirmed that SpaceX entered the Nasdaq-100 and the Invesco QQQ ETF with a 1.27% weight on July 7. SpaceX was also added to other broad-market benchmarks soon after its IPO. That means investors who hold funds tracking the Nasdaq-100, certain total-market indexes or portfolios that contain those funds may own a small amount of SpaceX without ever having purchased the stock directly.
The exposure is not universal. A retirement account invested only in an S&P 500 index fund would not have received direct SpaceX exposure merely because the company entered the Nasdaq-100. The S&P 500 retained its existing eligibility rules rather than fast-tracking SpaceX. Whether a worker owns SpaceX through a 401(k) therefore depends on the specific funds and benchmarks available inside the plan.
That distinction has become part of a broader political argument over Musk’s wealth. Sen. Bernie Sanders, the independent from Vermont who describes himself as a democratic socialist, has repeatedly argued that the extraordinary growth of billionaire fortunes reflects an economy that concentrates too much ownership and power in too few hands.
In June, Sanders introduced the American AI Sovereign Wealth Fund Act. The proposal would impose a one-time tax equal to 50% of the outstanding equity of qualifying large AI companies, with the tax paid in shares rather than cash. The shares would be transferred to a federal sovereign wealth fund and managed by a seven-member Independent Commission for Democratic AI.
Under Sanders’ bill summary, companies involved in AI data centers, AI computing infrastructure, AI services or advanced robotics would become subject to the tax after reaching at least $200 million in related annual gross receipts. Large companies combining AI and non-AI businesses would also be required to separate those operations so that the public ownership stake applies to the AI business. Sanders’ office estimates that the fund could initially be worth about $7 trillion.
The proposal calls for the fund to distribute 5% of its market value each year to the Treasury for direct payments and other measures intended to raise living standards, including access to health care, education and housing. Sanders’ office says the initial annual payout could be large enough to support a direct payment of more than $1,000 per person if its valuation assumptions prove correct.
The timing matters. Sanders introduced the legislation on June 18, eight days before Nasdaq announced SpaceX’s addition to the Nasdaq-100. There is no evidence that the bill was introduced in response to SpaceX entering retirement portfolios. The two issues have since become intertwined politically because Musk is both the dominant shareholder in SpaceX and one of the central figures Sanders cites in his campaign against concentrated wealth.
That argument resurfaced in early September when Sanders wrote on X: “One man (Mr. Musk) owns more wealth than the bottom half of American households.” He added that 60% of Americans live paycheck to paycheck, nearly 800,000 are homeless and 85 million are uninsured, concluding, “We can do better. We must do better.”
Several of those claims require context. The homelessness figure is broadly consistent with the Department of Housing and Urban Development’s 2024 Point-in-Time count, which found 771,480 people experiencing homelessness on a single night in January 2024. The “paycheck to paycheck” figure depends heavily on the survey and definition used and should not be treated as a single official government statistic.
The health-insurance claim is more problematic as written. Sanders and his office have frequently cited roughly 85 million Americans as “uninsured or underinsured,” but his recent X post said “85 million are uninsured.” Census Bureau data show that 92% of the U.S. population, or about 310 million people, had health insurance for some or all of 2024. The available federal data therefore do not support a claim that 85 million Americans are simply uninsured.
Sanders’ statement that Musk alone owns more wealth than the bottom half of American households also does not match the Federal Reserve’s standard household-net-worth measure. Federal Reserve Distributional Financial Accounts data for the first quarter of 2026 put the combined net worth of the bottom 50% of U.S. households at about $4.27 trillion. Forbes estimated Musk’s net worth at roughly $929 billion in mid-September. The dates and methodologies are not identical, but the gap is large enough that the claim is not supported by those measures.
Musk, meanwhile, has pushed back on descriptions of his fortune as though it were a giant cash balance. “I have stock in SpaceX and Tesla, not some big pile of cash,” he wrote on X. “As my companies do more and more useful things, their value increases proportionate to their projected usefulness. All shareholders benefit along the way, including most retirement programs.”
The basic distinction Musk makes is real: billionaire net-worth estimates are largely valuations of ownership interests, not bank balances. Forbes attributes most of Musk’s fortune to his holdings in SpaceX and Tesla, meaning his paper wealth can rise or fall sharply as the market values of those companies change. SpaceX’s public listing made that connection more visible because a portion of the same company is now owned by public-market investors, including passive funds used by retirement savers.
But the existence of retirement-account exposure does not settle the policy dispute. A worker owning a tiny fraction of SpaceX through an index fund is economically different from a founder controlling a very large personal stake in the company. Likewise, the fact that Musk’s wealth is primarily stock does not make that wealth imaginary; equity can carry voting power, collateral value and the potential to be sold or borrowed against, even when it is not held as cash.
Sanders’ proposal would go much further than ordinary taxation by transferring a major ownership stake in qualifying AI companies to a government-managed fund. Supporters frame that idea as a way to give the public a direct share of wealth generated by transformative technology. Critics are likely to focus on the forced transfer of equity, government voting power in private companies, possible effects on investment incentives and the practical difficulty of separating AI businesses from broader corporate operations.
The debate also shows why broad labels can obscure more than they explain. Sanders’ proposal is highly interventionist, but sovereign wealth funds themselves exist in market economies around the world and in U.S. states such as Alaska. Whether his specific 50% equity-tax model would work, survive legal challenges or attract enough political support is a separate question from whether public investment funds can exist within capitalist systems.
For retirement savers, the immediate issue is much simpler. SpaceX is now a public company and a component of the Nasdaq-100, and it has entered other broad-market benchmarks as well. Investors who want to know whether they own it indirectly need to check the actual holdings and benchmark methodology of their 401(k), IRA, target-date fund or ETF rather than assuming all retirement accounts have the same exposure.
That reality connects the market story to the political one without making them the same story. SpaceX’s IPO has spread a slice of Musk’s company across millions of investment accounts, while Sanders is separately arguing that the public should own a much larger share of the wealth generated by dominant technology companies. The fight is ultimately over how ownership, risk and rewards should be distributed - and the fact that many ordinary savers now own a small piece of SpaceX makes that argument more tangible than it was when the company was private.
"🚨 BRANSON'S SCATHING ATTACK! — HE BLASTS TRUMP OVER PUTIN TIES AND URGES EUROPE TO STAND FIRM!"
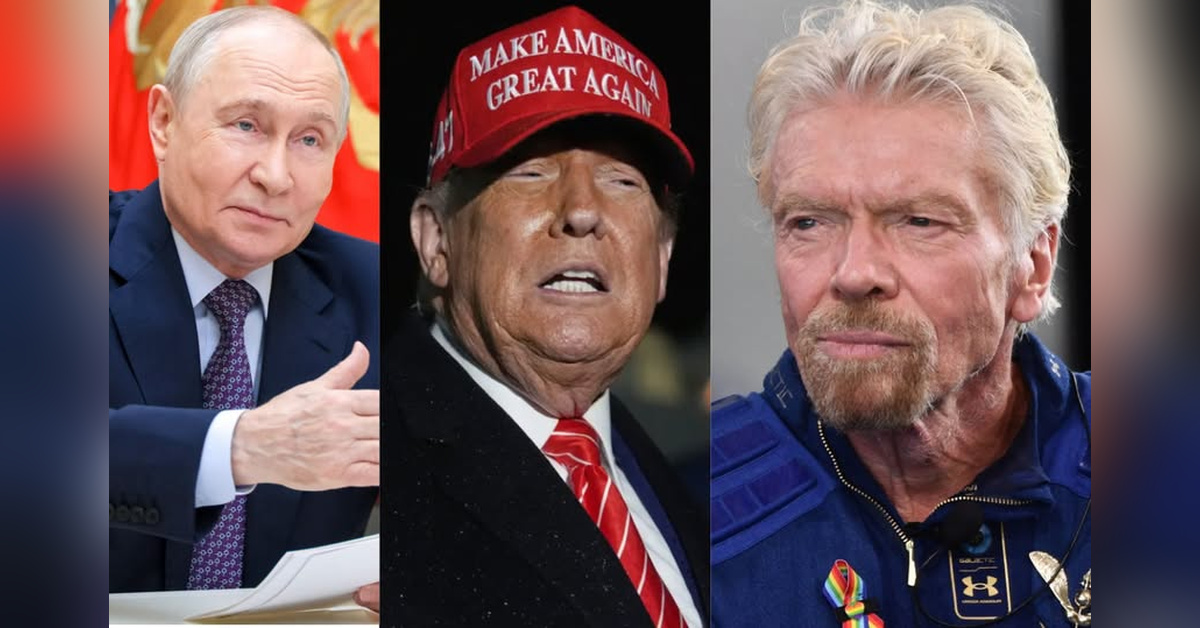
British billionaire Sir Richard Branson has launched a fierce public attack on Donald Trump, accusing the U.S. administration of appeasing dictators and putting personal preferences ahead of American and allied interests.
The Virgin Group founder made his criticism in a LinkedIn post published this week, questioning why Trump appeared so willing to accommodate Russian President Vladimir Putin while Ukraine continues to face Russia’s invasion.
Branson described the administration as an “appeaser to autocrats and dictators,” arguing that its approach could weaken confidence among America’s traditional allies and undermine the interests of democratic nations.
He also raised a pointed question about the president’s relationship with Putin, asking why Trump seemed to flatter the Russian leader despite the continuing war and widespread international concern over Moscow’s actions.
The remarks come amid renewed controversy over a reported agreement involving Russian diesel supplies and a temporary easing of U.S. sanctions on Russian energy exports.
Trump has defended the arrangement as beneficial to fuel markets, while critics argue that allowing Russian energy revenues to flow could indirectly help Moscow sustain its war effort.
Branson called the deal deeply hypocritical, pointing to the contrast between Washington’s previous willingness to penalize countries purchasing Russian energy and its own decision to ease restrictions.
His criticism extended beyond energy policy. He also condemned Trump’s public attacks on Ukrainian President Volodymyr Zelenskyy, describing the administration’s treatment of Ukraine as a betrayal during a period of war and suffering.
The billionaire’s intervention follows mounting concern in Kyiv and across Europe about the durability of American support for Ukraine, particularly as diplomatic efforts have struggled to produce a lasting settlement.
Branson also expressed alarm about reports involving restrictions on Starshield services used by Ukraine, a technology issue that has raised questions about the country’s access to crucial battlefield communications.
Some of Branson’s claims about the consequences of satellite-service restrictions have not been independently confirmed, and the details of decisions involving military communications remain disputed.
He urged European leaders to respond more decisively, arguing that the continent cannot simply wait for Washington to determine the future of Ukraine’s security and its broader relationship with Russia.
His proposed response reportedly included considering the use of frozen Russian assets to support Ukraine and supplying more advanced weapons, measures that would intensify the confrontation with Moscow.
The comments place Branson among a relatively small group of prominent business leaders willing to criticize Trump directly over foreign policy, despite the political and commercial sensitivities surrounding such interventions.
Branson has previously spoken out in support of Ukraine and criticized approaches that he believes would pressure Kyiv into accepting an unfavorable peace agreement with Russia.
The latest dispute also comes at a politically sensitive moment in the United States, with congressional midterm elections approaching and foreign policy increasingly intertwined with domestic debates over leadership and national priorities.
Supporters of Trump’s approach may argue that direct engagement with Moscow and energy-market flexibility can serve American interests, even when such policies provoke disagreement among allies.
Critics counter that concessions to Russia risk weakening deterrence and sending an unsettling message to countries relying on the United States for diplomatic, economic and military support.
The disagreement reflects a broader debate over whether negotiations and economic pragmatism can help end the war—or whether they could give Moscow additional leverage without securing meaningful concessions.
For Ukraine, the stakes remain immediate: continued military pressure, uncertainty over international support and the search for a settlement that preserves its sovereignty remain central concerns.
Branson’s intervention adds another prominent voice to the dispute, challenging the White House’s handling of Russia and demanding a stronger response from Europe as the conflict continues.