It’s Over — House Drops Stunning 396-13 Vote
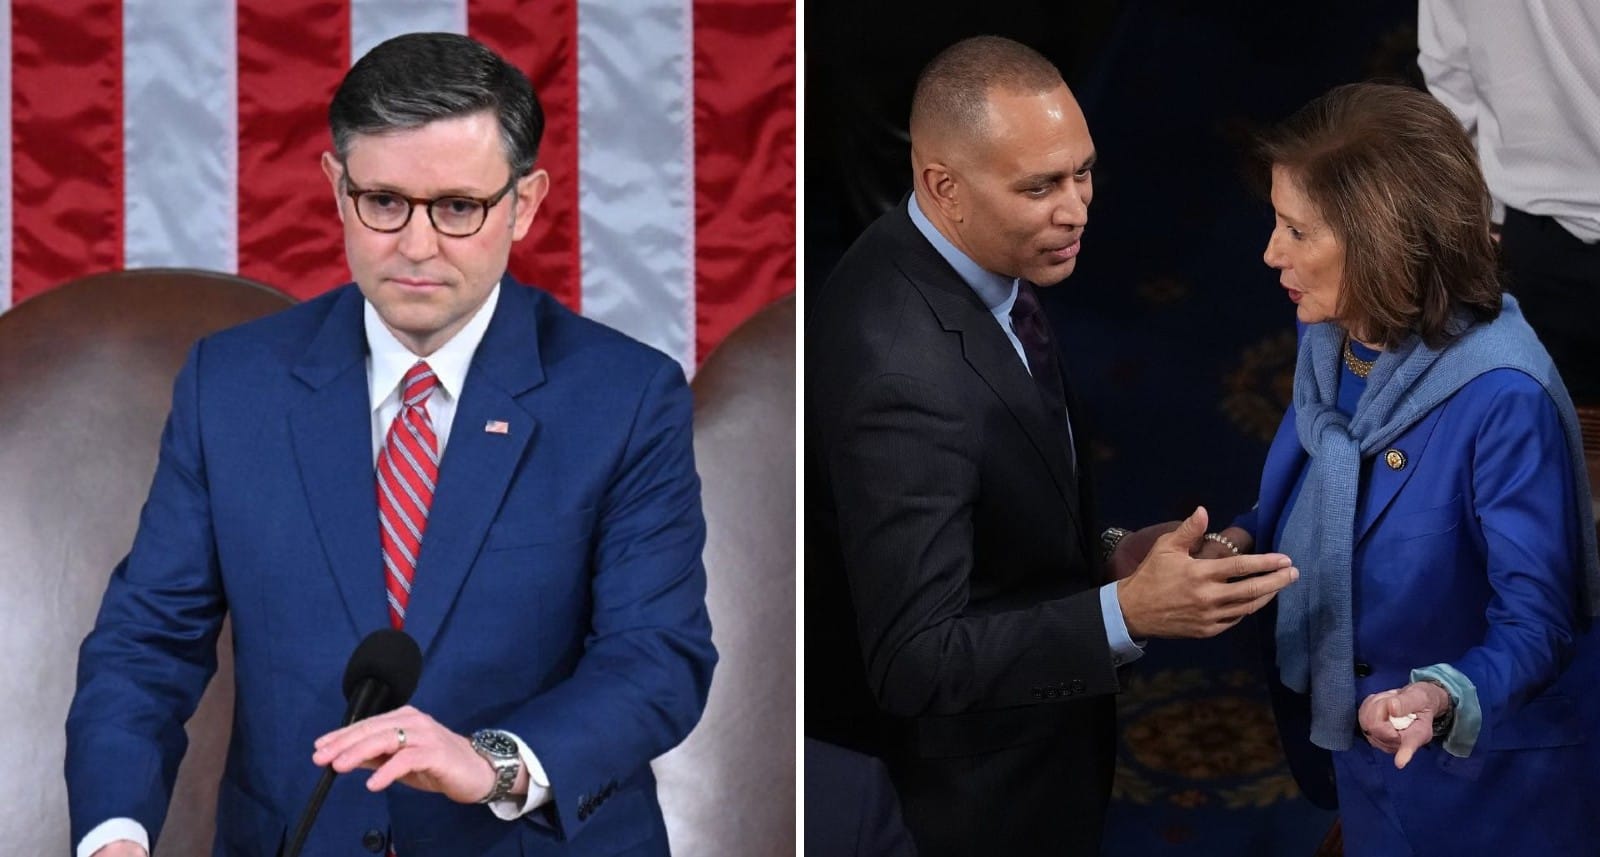
A sweeping bipartisan housing package that first drew national attention with a 396-13 House vote has now completed an unusually complicated path through Congress and become federal law, creating new restrictions on large institutional investors while pursuing a broader strategy of increasing housing supply, reducing regulatory barriers and expanding access to financing.
The 21st Century ROAD to Housing Act became law on July 11 after months of negotiations between the House and Senate. Its enactment gives lawmakers in both parties a major legislative achievement on an issue that has become one of the most persistent cost-of-living pressures facing American families.
The legislation is much broader than the political fight over corporate ownership of single-family homes. It includes dozens of housing and community-banking provisions dealing with construction, manufactured and modular housing, federal housing programs, mortgage access, environmental reviews, local planning and the flow of credit to builders and homebuyers.
But the provision receiving the most public attention is the section titled “Homes Are for People, Not Corporations,” which limits additional purchases of certain single-family homes by large institutional investors.
That restriction reflects a rare area of agreement among Republicans, Democrats, progressive housing advocates and many voters who believe families should not have to compete against large investment firms for the same homes.
A Bipartisan Policy Center survey conducted in late April found that 70 percent of registered voters supported a federal prohibition preventing large corporations and investors that already own 350 or more single-family homes from buying additional properties. The same poll found that 89 percent of voters wanted the House and Senate to work together on legislation addressing housing affordability.
The final law uses the 350-home threshold as part of its definition of a large institutional investor. It generally prohibits covered for-profit entities from purchasing additional qualifying single-family homes once the restriction takes effect, although the statute includes a number of exceptions and does not require investors to sell homes they owned before enactment.
The prohibition is scheduled to take effect 180 days after enactment, placing the effective date in early January 2027. It is also temporary rather than permanent: the investor-purchase restriction and related enforcement provisions sunset 15 years after the effective date unless Congress acts again.
The definition of a covered single-family home generally includes residential structures containing no more than two dwelling units and excludes manufactured homes. The law also contains exceptions intended to avoid discouraging new construction or disrupting certain financing and redevelopment activities.
Those exceptions are important because lawmakers spent months arguing over whether an overly broad institutional-investor ban could unintentionally reduce rental supply or discourage capital from financing new housing.
Under the final framework, large investors may still participate in specified categories such as qualifying build-to-rent activity, certain renovate-to-rent transactions and programs structured to create eventual homeownership opportunities. The law therefore attempts to distinguish between investors competing with individual buyers for existing homes and capital used to create or rehabilitate additional housing supply.
That distinction became one of the central negotiating issues between the House and Senate.
On March 12, the Senate passed an earlier version of the legislation by an 89-10 vote. That version contained a more aggressive institutional-investor framework, including a seven-year resale requirement attached to certain categories of otherwise permitted purchases.
The House rejected that approach. On May 20, representatives approved an amended version of the ROAD to Housing Act by the strikingly bipartisan margin of 396-13. House negotiators removed the seven-year resale requirement and revised other provisions they said could discourage investment in rental housing or new construction.
The House vote was the moment the bill became a major national political story. Speaker Mike Johnson called rising housing costs and inadequate supply problems that affect nearly every American family and described the measure as a bipartisan package intended to put more families into homes.
House Majority Leader Steve Scalise similarly argued that lowering housing costs was an issue with unusually broad public appeal. House Financial Services Committee Chairman French Hill said the bill was designed to expand homeownership, reduce regulations that increase costs and prevent institutional investors from outcompeting families seeking to buy homes.
The Trump administration initially endorsed the revised House version. A White House official said at the time that the administration supported the House bill after changes were made, and lawmakers emphasized that its investor restrictions reflected President Donald Trump’s call to reduce competition between large financial firms and individual homebuyers.
The 396-13 vote did not end the legislative fight because the House had amended a bill already passed by the Senate. The upper chamber still had to decide whether to accept the House changes, restore its own provisions or negotiate a compromise.
The seven-year resale requirement became one of the most important disputes. Some supporters of stronger restrictions wanted investors to have to return homes to the individual-buyer market after a limited period. House lawmakers and industry groups warned that such a rule could reduce investment in rental supply and produce unintended consequences for tenants and housing development.
The final compromise largely followed the House approach. On June 16, Senate Banking Committee Chairman Tim Scott, Ranking Member Elizabeth Warren, Hill and House Financial Services Ranking Member Maxine Waters released a negotiated bicameral package.
That agreement preserved restrictions on future purchases by large institutional investors while eliminating the forced seven-year resale requirement and protecting qualifying build-to-rent activity. It also retained community-banking provisions that House negotiators considered important to financing housing construction.
The Senate passed the compromise on June 22 by an 85-5 vote. The House then approved the final text the following day by a 358-32 vote, sending the measure to the White House.
The result was a rare bipartisan legislative coalition. Scott and Warren, who differ sharply on many economic issues, were central Senate negotiators. Hill and Waters played parallel roles in the House. The final package combined Republican emphasis on deregulation and community-bank lending with Democratic priorities involving affordable housing, consumer access and restrictions on large corporate homebuyers.
The bill’s arrival at the White House produced one final twist.
Trump had supported major elements of the legislation and his administration had endorsed earlier versions, but he ultimately declined to sign the final bill after tying his support to congressional action on separate election legislation known as the SAVE America Act.
Congress did not pass that election measure on Trump’s preferred timetable. The president nevertheless did not veto the housing package. Because Congress remained in session and Trump neither signed nor returned the bill within the constitutionally prescribed 10-day period, Sundays excepted, the 21st Century ROAD to Housing Act became law without his signature on July 11.
That sequence makes the measure unusual politically. Republican congressional leaders continue to describe it as advancing Trump’s housing agenda, particularly the institutional-investor restriction, even though the president allowed the final bill to become law without formally signing it.
The new law’s most consequential provisions may ultimately be the supply-side reforms that received less attention than the corporate-homebuyer debate.
House negotiators estimated that the United States faces a housing shortage of as many as 5.5 million units. Economists and housing researchers disagree about the exact national shortfall, but there is broad agreement that many metropolitan areas have failed to build enough homes to keep pace with population growth, household formation and demand.
The ROAD to Housing Act attempts to attack that shortage through numerous smaller policy changes rather than a single large federal construction program.
One set of provisions encourages ready-to-use and pre-approved housing designs, which supporters say can shorten permitting timelines and reduce design costs. Other sections promote modernization of housing processes, expand local capacity to produce affordable homes and encourage jurisdictions to examine regulatory barriers that make construction slower or more expensive.
The law does not directly override local zoning. Instead, it uses federal studies, technical assistance, incentives and planning tools to encourage states and municipalities to consider reforms involving density, lot sizes, transit-oriented development, permitting, impact fees and other local rules that influence how much housing can be built.
That approach helped attract support from organizations representing mayors and local governments that have historically resisted federal attempts to dictate zoning policy.
Manufactured and modular housing receive significant attention as well. The law updates federal definitions and financing rules intended to make factory-built housing easier to produce and finance, while directing federal agencies to examine barriers that have limited the use of modular construction.
Supporters argue that factory-built housing can lower construction costs and expand affordable options, particularly in rural communities and markets where traditional site-built construction has become too expensive for many buyers.
The legislation also modernizes the HOME Investment Partnerships Program, the federal government’s largest block-grant program focused on producing affordable housing. Lawmakers described the changes as the program’s most substantial update in decades.
Other provisions seek to reduce delays in federal inspections, improve financing for small-dollar mortgages, expand the pool of qualified appraisers and create new mechanisms that could help lower-income families build savings toward homeownership.
Community banks are another major part of the package. The law includes a collection of provisions intended to reduce regulatory burdens on smaller financial institutions and expand their ability to provide mortgages, construction loans and other credit in local markets.
Supporters argue that community banks are particularly important in rural areas and smaller cities where large national lenders may have limited presence. Housing advocates have long warned that financing constraints can prevent builders from adding homes even where demand is strong.
The law also addresses multifamily housing. Provisions increase or modernize certain financing limits and federal tools intended to support apartment construction, reflecting the reality that housing affordability depends on both homeownership and rental supply.
The institutional-investor rules, therefore, sit inside a much larger theory of the housing problem: limiting corporate competition for some single-family homes may help individual buyers, but sustainable affordability also requires building substantially more housing.
That is why the final compromise rejected the broadest version of the divestiture concept. House negotiators argued that forcing investors to dispose of permitted rental properties on a fixed timetable could reduce the rental stock or create instability without necessarily increasing construction.
Progressives who favored tougher restrictions viewed the House changes as a retreat from a stronger anti-corporate-landlord approach. But Warren ultimately supported the negotiated package, helping deliver the overwhelming Senate vote that cleared the way for enactment.
The investor restrictions also contain more nuance than political slogans such as “ban Wall Street from buying homes” suggest. The law does not prohibit every company, landlord or investment partnership from owning rental houses. It targets entities meeting the statutory definition of a large institutional investor and contains detailed exceptions for particular types of acquisitions.
Small landlords and families owning one or several rental properties are not the primary target of the provision. The 350-home threshold reflects an attempt to focus federal restrictions on larger firms with significant residential portfolios.
The law also does not require covered firms to liquidate the single-family homes they already owned when it was enacted. The central restriction is forward-looking, limiting covered purchases after the effective date except where an acquisition falls within a statutory exception.
That point is important for renters. Earlier debate sometimes created the impression that the legislation would force mass sales of thousands of currently occupied rental homes. The final law does not impose such a blanket divestiture requirement.
Supporters say the narrower structure protects renters from unnecessary disruption while still preventing large firms from continually expanding existing-home portfolios in direct competition with families.
Critics from the real-estate industry argue that institutional investors represent only one part of a much larger housing shortage and that restrictions on capital can have unintended consequences. Some researchers also note that investor concentration varies greatly by region and that large firms own only a minority of the nation’s overall single-family housing stock.
A 2026 Government Accountability Office review found that institutional ownership is especially concentrated in selected metropolitan markets and grew after the foreclosure crisis, when investors purchased large numbers of distressed homes. The effects on local prices, rents and neighborhood conditions can differ depending on market conditions and investor behavior.
The polling behind the restriction also contains an important qualification. Although the Bipartisan Policy Center survey found 70 percent support for limiting additional purchases by large investors, nearly one-third of supporters said they would become less supportive if the policy reduced the supply of rental homes.
That finding helps explain why congressional negotiators attempted to preserve build-to-rent and other supply-creating exceptions rather than treating every institutional purchase in the same way.
A separate controversy almost derailed the House vote despite having little to do with housing: central bank digital currency.
The ROAD to Housing Act includes a temporary prohibition on the Federal Reserve issuing a central bank digital currency, commonly known as a CBDC. The restriction expires at the end of 2030.
Thirteen Republicans voted against the May House version, with several conservative members arguing that a temporary ban was inadequate and could effectively establish a date after which a future Federal Reserve might be free to launch a government-backed digital dollar.
Rep. Warren Davidson of Ohio became one of the most outspoken critics. He argued that a temporary prohibition offered political cover in the short term while leaving a future path open after 2030 and said Congress should either make the ban permanent or remove the provision from the housing bill.
The CBDC language nevertheless survived into the final law. Conservative lawmakers have since introduced separate legislation seeking to make the prohibition permanent, demonstrating that the dispute was postponed rather than fully resolved by the housing package.
The overwhelming bipartisan support for the ROAD to Housing Act is especially notable because housing policy has increasingly become entangled with broader partisan disputes over zoning, federal spending, private equity, environmental regulation and the proper role of the federal government.
Republicans can point to the law as evidence that they addressed a major affordability issue before the 2026 midterms. The package includes deregulation, community-bank relief and a restriction aligned with Trump’s campaign message about institutional investors.
Democrats can point to their own role in writing and passing the legislation. Warren and Waters were among the principal negotiators, and Democratic votes were essential to the enormous margins in both chambers.
That shared ownership makes the politics less simple than either party might prefer. The bill was neither a purely Republican housing plan nor a Democratic one. It was assembled from legislation and priorities developed across multiple Congresses and ultimately survived because leaders in both parties accepted compromises.
The more important question is whether the law will actually make housing meaningfully cheaper.
There is no immediate guarantee. Housing markets respond slowly to changes in regulation, financing and construction. A measure enacted in July cannot instantly create millions of new homes or reverse years of price growth.
Many provisions require federal agencies to issue regulations, conduct studies, launch pilot programs or revise administrative processes. The investor-purchase restriction itself does not begin until 180 days after enactment. New construction encouraged by permitting or financing reforms may take years to reach the market.
Mortgage rates, land prices, labor costs, building materials, insurance premiums and local zoning will continue to influence affordability independently of the federal law. In some expensive regions, those factors may overwhelm the impact of individual federal reforms.
But supporters argue that the law should be evaluated as structural housing policy rather than a short-term rebate. By making it easier to finance, permit and construct housing while limiting some competition from large investors, they hope to increase supply and improve the position of individual buyers over time.
The political appeal of that argument is clear. Housing has become one of the few economic issues capable of uniting renters, first-time buyers, young families, seniors trying to downsize and existing homeowners worried that their children will never be able to purchase a home.
The BPC survey found that 79 percent of voters considered housing costs an extremely or very important issue, and 63 percent said they would be more likely to support a lawmaker who helped pass legislation designed to build more affordable homes and lower costs.
Those numbers explain why lawmakers were willing to keep negotiating after the 396-13 House vote rather than allow disputes over investor rules, banking provisions or CBDC language to kill the package.
The final law is therefore more significant than the original House headline suggested. The May vote was not the end of the process but the beginning of the decisive round of bargaining.
By late June, the Senate and House had resolved the major institutional-investor disagreement, restored community-banking provisions, preserved a temporary CBDC restriction and agreed on a broad set of more than 45 housing reforms.
By July 11, the package had become law even without a presidential signature.
The result is one of the most substantial bipartisan federal housing measures in decades. It restricts future expansion by very large single-family-home investors, protects specified supply-producing investment, modernizes federal housing programs and attempts to reduce barriers that have slowed construction across the country.
Whether those reforms ultimately deliver lower prices will depend heavily on implementation by federal agencies, participation by states and local governments, private-sector construction and the broader economy.
But the legislative outcome is no longer uncertain. The 21st Century ROAD to Housing Act did not stall in the Senate after the 396-13 House vote. Congress continued negotiating, passed a final compromise by overwhelming margins and placed a new federal housing framework into law.
May you like
For lawmakers heading into the midterm elections, that provides a tangible accomplishment to campaign on. For homebuyers and renters, the more consequential test begins now: whether a bipartisan promise to build more, finance more and reduce large-investor competition can translate into measurable improvement in the housing market.