"🚨 POLITICAL SHOCKER! — A BRUTAL DEMAND: TRUMP WANTS ANSWERS ABOUT ILHAN OMAR'S $30 MILLION FINANCIAL DISCLOSURE!"
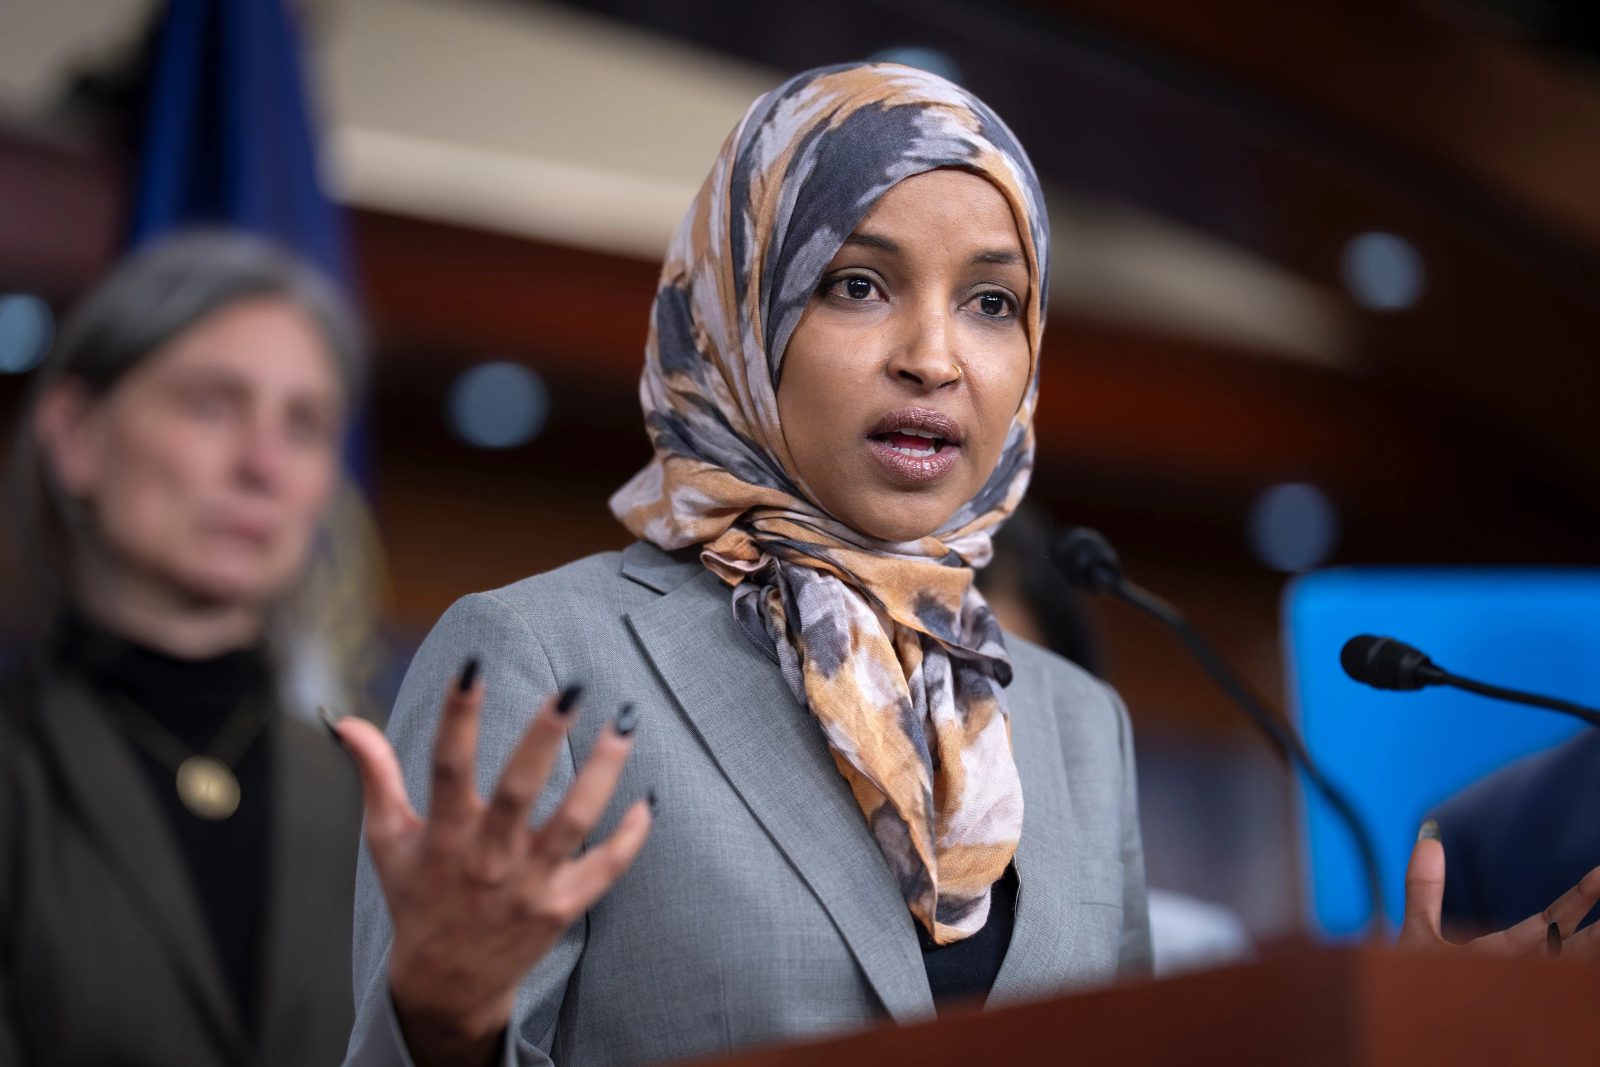
“America wants answers, and we want them, NOW!” President Donald Trump declared as questions surrounding Representative Ilhan Omar’s financial disclosures returned to the national spotlight. At the center of the controversy is a striking discrepancy: a filing once placed the value of businesses connected to Omar’s husband as high as $30 million, only for a later amendment to report a dramatically lower range of assets.
Now, with a federal prosecutor confirming a new investigation into Omar’s financial disclosures, the dispute has entered another chapter. What caused the original figures to change so dramatically—and will investigators uncover evidence that goes beyond an accounting mistake?
Those questions have fueled a political confrontation involving Trump, congressional Republicans and the Minnesota Democrat. But the difference between a suspicious-looking filing and proven financial misconduct remains critical.
Trump’s Demand Puts the $30 Million Figure Back in Focus
Trump publicly questioned Omar’s financial disclosures after the discrepancy between the original filing and the amended version attracted renewed scrutiny.
The original disclosure reported that two businesses associated with her husband, Tim Mynett, were valued in a range that reached $30 million. The companies’ reported value had appeared to rise sharply compared with an earlier disclosure, prompting questions from Republicans about how the figures had been calculated.
In an October 2026 report, The Washington Post described Trump’s demand for answers and reported that U.S. Attorney Jeanine Pirro had confirmed a separate investigation into the financial disclosures.
The issue is politically sensitive because members of Congress must file financial disclosures intended to provide transparency about their assets, income and financial interests. Significant inaccuracies can raise legitimate questions about compliance and the reliability of the information provided.
But the original filing did not establish that Omar personally possessed $30 million in cash. The reported figures concerned the estimated value of businesses connected to her husband, and the disclosure used valuation ranges rather than a precise account of liquid wealth.
That distinction matters when evaluating claims about how much money a lawmaker actually has.
Why the Original Filing Was Amended
In April 2026, Omar amended the financial disclosure after the initial figures drew attention.
The revised form listed the couple’s joint assets in a range of approximately $18,004 to $95,000. The valuations for Mynett’s two businesses were listed as “none,” while the amended filing also reported an income range associated with the businesses.
Omar’s office attributed the original discrepancy to an accounting error. Her representatives said the initial filing had overstated the couple’s assets and disputed the suggestion that Omar had suddenly become a multimillionaire.
The change was substantial enough to attract attention from Republican lawmakers, including House Oversight Committee Chairman James Comer, who had requested records related to businesses associated with Mynett.
The central question is whether the initial figures resulted from a mistake in calculating or reporting business valuations, or whether any information was knowingly misrepresented. The size of the discrepancy alone cannot establish intent.
Financial disclosures can be complicated, particularly when they involve privately held businesses whose values may depend on estimates rather than publicly traded share prices. Even so, public officials are responsible for ensuring that their filings comply with disclosure requirements, and significant corrections can warrant scrutiny.
A New Federal Investigation Raises the Stakes
On October 13, 2026, Pirro said her office was investigating Omar’s financial disclosures. The announcement came one day after federal agents searched Omar’s Washington, D.C., residence in connection with a separate investigation involving her immigration paperwork.
The timing brought two distinct matters into the same political conversation. One concerns allegations about historical immigration documents; the other concerns the financial disclosure discrepancy involving businesses connected to Omar’s husband.
The investigations should not be treated as proof of one another. The search of Omar’s home in the immigration inquiry does not establish that she committed financial misconduct, and the financial investigation does not prove the immigration allegations.
Omar has rejected accusations of wrongdoing. Her office has pointed to the amended disclosure and the earlier congressional watchdog review as reasons the financial controversy should not be portrayed as established misconduct.
In September 2026, Omar’s office said the Office of Congressional Conduct had recommended dismissing allegations arising from the disclosure error. That review was a significant development, but Pirro’s later announcement indicated that a separate federal inquiry was being pursued.
The precise scope of the new investigation and what evidence prosecutors are examining have not been fully established in public reporting.
What Does the $30 Million Figure Actually Mean?
The phrase “missing $30 million” suggests that a large sum of money disappeared. The available records do not establish that.
The original disclosure reported a valuation range for businesses in which Mynett held interests. The amended filing later reported substantially lower joint assets and removed the earlier business valuations. That is a major difference between two filings, but it is not the same as evidence that $30 million was stolen, concealed or transferred elsewhere.
To establish financial wrongdoing, investigators would need to examine the underlying records, the methods used to value the businesses, the information provided to the accountant and whether any errors were knowingly made.
They may also need to distinguish between a business’s estimated value, its income, its liabilities and the value of an individual’s ownership stake. Those figures can differ significantly.
The public deserves accurate financial disclosures from elected officials. At the same time, a responsible account of the controversy must separate verified information from allegations and avoid treating a disputed valuation as proof of criminal conduct.
The Political Battle Is Far From Over
The dispute has become another point of conflict between Trump and Omar, who has frequently criticized his administration. Trump and his allies have pressed for closer scrutiny of her finances, while Omar has described the attention as politically motivated.
Republicans have argued that the initial filing deserves answers because the reported valuations changed so dramatically. Omar’s office has maintained that the amendment corrected an accounting mistake and has cited the earlier watchdog recommendation to dismiss the allegations.
Those positions do not resolve the factual questions at the center of the new federal investigation. The answer depends on the underlying records and the findings of the authorities reviewing them.
The distinction is especially important as the November 2026 midterm elections approach. Political rhetoric can intensify scrutiny, but it cannot substitute for documentary evidence or a legal finding.
What Happens Next?
The new investigation could examine how the original valuations were calculated, what information was supplied to the accountant, and whether the amended disclosure accurately reflects the couple’s financial interests.
If investigators find evidence of a deliberate false statement or another violation, prosecutors would have to establish the relevant elements under the applicable law. If the discrepancy resulted from an accounting error, the evidence would need to support that explanation as well.
Neither conclusion should be assumed in advance.
For now, the established facts are narrower than the most dramatic versions of the story suggest: an original disclosure reported business valuations reaching $30 million; Omar later amended the filing and attributed the discrepancy to an accounting error; a congressional watchdog recommended dismissing allegations related to the filing; and a federal prosecutor subsequently confirmed a new investigation.
Trump’s demand has ensured that the controversy remains in the spotlight. The more consequential development will be whether investigators produce evidence that explains the discrepancy and establishes whether any rules were violated.
Was the $30 million discrepancy an accounting mistake, or will the new investigation uncover evidence that changes the understanding of Omar’s financial disclosures? That question remains open—and the answer must come from the records, not the political rhetoric surrounding them.
"🚨 BRANSON'S SCATHING ATTACK! — HE BLASTS TRUMP OVER PUTIN TIES AND URGES EUROPE TO STAND FIRM!"
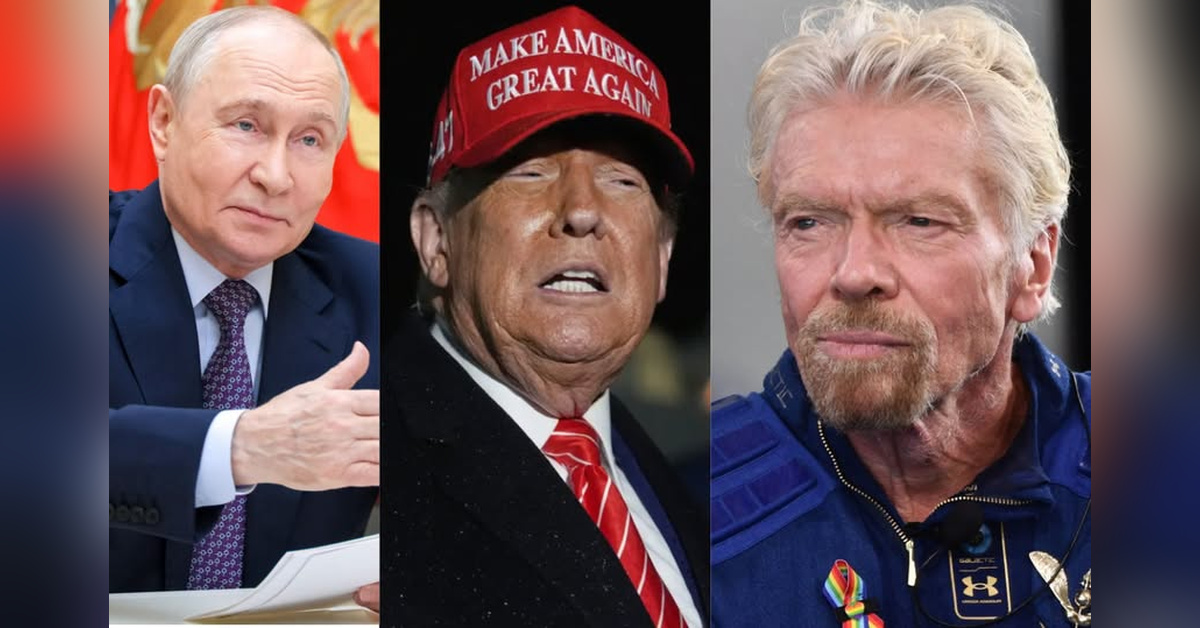
British billionaire Sir Richard Branson has launched a fierce public attack on Donald Trump, accusing the U.S. administration of appeasing dictators and putting personal preferences ahead of American and allied interests.
The Virgin Group founder made his criticism in a LinkedIn post published this week, questioning why Trump appeared so willing to accommodate Russian President Vladimir Putin while Ukraine continues to face Russia’s invasion.
Branson described the administration as an “appeaser to autocrats and dictators,” arguing that its approach could weaken confidence among America’s traditional allies and undermine the interests of democratic nations.
He also raised a pointed question about the president’s relationship with Putin, asking why Trump seemed to flatter the Russian leader despite the continuing war and widespread international concern over Moscow’s actions.
The remarks come amid renewed controversy over a reported agreement involving Russian diesel supplies and a temporary easing of U.S. sanctions on Russian energy exports.
Trump has defended the arrangement as beneficial to fuel markets, while critics argue that allowing Russian energy revenues to flow could indirectly help Moscow sustain its war effort.
Branson called the deal deeply hypocritical, pointing to the contrast between Washington’s previous willingness to penalize countries purchasing Russian energy and its own decision to ease restrictions.
His criticism extended beyond energy policy. He also condemned Trump’s public attacks on Ukrainian President Volodymyr Zelenskyy, describing the administration’s treatment of Ukraine as a betrayal during a period of war and suffering.
The billionaire’s intervention follows mounting concern in Kyiv and across Europe about the durability of American support for Ukraine, particularly as diplomatic efforts have struggled to produce a lasting settlement.
Branson also expressed alarm about reports involving restrictions on Starshield services used by Ukraine, a technology issue that has raised questions about the country’s access to crucial battlefield communications.
Some of Branson’s claims about the consequences of satellite-service restrictions have not been independently confirmed, and the details of decisions involving military communications remain disputed.
He urged European leaders to respond more decisively, arguing that the continent cannot simply wait for Washington to determine the future of Ukraine’s security and its broader relationship with Russia.
His proposed response reportedly included considering the use of frozen Russian assets to support Ukraine and supplying more advanced weapons, measures that would intensify the confrontation with Moscow.
The comments place Branson among a relatively small group of prominent business leaders willing to criticize Trump directly over foreign policy, despite the political and commercial sensitivities surrounding such interventions.
Branson has previously spoken out in support of Ukraine and criticized approaches that he believes would pressure Kyiv into accepting an unfavorable peace agreement with Russia.
The latest dispute also comes at a politically sensitive moment in the United States, with congressional midterm elections approaching and foreign policy increasingly intertwined with domestic debates over leadership and national priorities.
Supporters of Trump’s approach may argue that direct engagement with Moscow and energy-market flexibility can serve American interests, even when such policies provoke disagreement among allies.
Critics counter that concessions to Russia risk weakening deterrence and sending an unsettling message to countries relying on the United States for diplomatic, economic and military support.
The disagreement reflects a broader debate over whether negotiations and economic pragmatism can help end the war—or whether they could give Moscow additional leverage without securing meaningful concessions.
For Ukraine, the stakes remain immediate: continued military pressure, uncertainty over international support and the search for a settlement that preserves its sovereignty remain central concerns.
Branson’s intervention adds another prominent voice to the dispute, challenging the White House’s handling of Russia and demanding a stronger response from Europe as the conflict continues.