"CANADA'S $1 TRILLION SUPERCYCLE: Mark Carney's Bold Move To Cut U.S. Dependence!"
Canada's C$1 Trillion Investment Pipeline Is Real - but the Trade-War 'Supercycle' Is Still a Bet on Execution
TD Economics has identified more than 300 publicly announced projects worth just over C$1 trillion across energy, mining, artificial intelligence, defence and transportation. The opportunity is unusually large, but much of the pipeline remains proposed or under review, foreign investment is mixed, and Canada's escalating trade conflict with the United States makes diversification more urgent rather than complete.
September 16, 2026
Canada is confronting one of the most consequential investment tests in its modern economic history: whether a worsening trade conflict with the United States can become the catalyst for a decade-long burst of capital spending rather than a drag on growth.
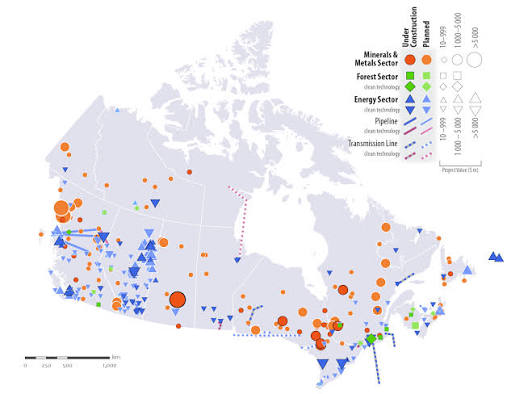
The scale of the opportunity is real. TD Economics said in an August 26 report that it had identified more than 300 publicly announced Canadian projects with estimated spending of just over C$1 trillion through 2035 and beyond. The projects span energy, mining and other resources, artificial intelligence, defence and transportation infrastructure.
TD's economists argued that, if Canada improves the conditions needed to turn proposals into actual construction, the country could enter an investment 'supercycle' lasting a decade or longer.
That conclusion has been widely amplified in political and social-media commentary, sometimes in much stronger terms than the underlying report supports. The trillion-dollar figure has been described as money already locked in, as a single government plan, and even as proof that global capital is abandoning the United States for Canada.
None of those descriptions is precise.
The C$1 trillion is best understood as a pipeline of announced potential investment. Some projects are already under construction. Some have regulatory approval but have not started building. Others remain under review. A large share are still proposals that may change, be delayed, shrink or never reach a final investment decision.
That difference is the central reality check behind Canada's investment story.
TD's inventory totals roughly C$1.1 trillion when its sector estimates are added together. Energy is the largest category at about C$363 billion, or roughly one third of the total. Defence follows at about C$281 billion. Artificial-intelligence projects account for approximately C$158 billion, resources for C$140 billion and transportation infrastructure for C$114 billion.
Those figures are large enough to matter even if only a portion of the pipeline is ultimately built. They also reveal why the idea of a Canadian investment supercycle has moved from political aspiration to a serious economic scenario.
The opportunity is unusually broad. Previous Canadian investment booms were often dominated by one sector, particularly commodities. TD's current list spans conventional energy, electricity generation, nuclear power, data centres, mines, ports, rail, highways, bridges and defence procurement.
TD estimated that more than C$190 billion of potential project spending could fall within its two-year forecast window, more than C$500 billion could occur during years three through ten, and about C$270 billion could continue beyond ten years.
The timing matters because the project status changes dramatically as the horizon lengthens.
In TD's analysis, projects already under construction dominate the near-term window. Proposed projects dominate the medium- and long-term categories. In other words, the further into the future the spending goes, the more dependent the forecast becomes on projects that still need financing, permits, partnerships, procurement decisions or market support.
That is why 'C$1 trillion in announced projects' is a defensible headline while 'C$1 trillion locked in' is not.
The resources category provides a good example. TD identified 86 mining projects, but explicitly described them as being at various stages of development. Treating all 86 as active construction would overstate the near-term economic impact.
Mining projects face some of the most complex execution risks in the entire pipeline. They can depend on commodity prices, electricity and road access, Indigenous consultation and partnerships, environmental approvals, financing conditions and long lead times before production begins.
Canada's critical-minerals ambitions make those projects strategically important, especially as Western governments try to reduce dependence on China for materials used in batteries, electronics, defence systems and clean-energy technologies.
But strategic importance does not eliminate project risk.
The same caution applies to energy projects, which account for the largest share of TD's pipeline.
Among the examples highlighted by TD is the Peace River Nuclear Power Project in northern Alberta. Energy Alberta is proposing a large nuclear station capable of producing up to 4,800 megawatts of electricity, potentially using four large reactors.
The project is real, and federal regulators formally moved it into the impact-assessment process in April 2026. But the Canadian Nuclear Safety Commission still lists it as a proposed facility in the planning phase of an integrated federal assessment.
That means it should not be described as an operating source of baseload electricity for data centres or industry. It is a potentially transformative project that is still years away from any possible operation and must pass regulatory, financing and construction tests first.
The distinction is important because large infrastructure announcements often acquire an economic life in headlines long before they acquire physical assets on the ground.
The same pattern applies to the artificial-intelligence component of Canada's investment push.
TD identified about C$158 billion in potential AI-related capital spending, much of it associated with data centres and the electricity infrastructure needed to support them. Canada has several advantages for that market, including abundant electricity in some provinces, cooler climates, land availability and proximity to U.S. technology markets.
But data-centre projects are also unusually power-hungry and can be constrained by transmission capacity, equipment shortages, grid interconnection delays and community opposition. The presence of a project in a public pipeline does not guarantee that the full announced capital budget will be spent.
Defence investment is another major source of the headline total.
TD's C$281 billion defence category reflects the scale of Canada's rearmament and modernization plans, including NORAD-related investment and other procurement commitments. Defence projects can be more durable than purely commercial proposals because government budgets provide a clearer source of demand, but procurement schedules can still shift and domestic industrial capacity can be a limiting factor.
Transportation infrastructure completes the picture. Port expansions, rail links, highways, bridges and trade corridors are central to Canada's diversification strategy because the country cannot meaningfully redirect exports without the physical capacity to move goods toward non-U.S. markets.
This is where the investment story and the trade-war story converge.
Prime Minister Mark Carney has framed the current confrontation with the United States not simply as a tariff dispute but as a warning against excessive economic dependence on one market.
In a September 8 national address, released as Canadian counter-tariffs took effect, Carney said the goal was to make Canada strong enough that 'no country can ever hold us hostage.' He also warned that the pivot would carry costs and would not be easy.
That language captures the government's strategic objective: diversification, not instant separation from the United States.
Canada remains deeply integrated with the U.S. economy. The United States accounted for roughly 72% of Canadian goods exports in 2025. More recent data show the share has fallen as exporters found additional non-U.S. markets, but the United States still buys by far the largest portion of Canadian merchandise exports.
In July 2026 alone, the United States still accounted for about two thirds of Canadian exports, even after months of trade disruption. Energy, autos, agriculture, manufacturing and cross-border supply chains remain tightly connected.
That makes any claim that Canada has already 'decoupled' from the United States economically implausible.
What has changed is the political incentive to reduce that dependence.
Canada imposed new counter-tariffs on September 8 after the United States placed 50% tariffs on C$27.6 billion of Canadian goods. Ottawa's measures apply rates of 15%, 25% and 50% to C$27.6 billion of U.S. products in sectors including steel, dairy, appliances, agricultural equipment, pulp and paper, plastics and electronics.
Washington then escalated the dispute further by announcing restrictions on Canadian products including certain dairy goods, most alcoholic beverages and some motorcycles, while also moving to exclude Canadian products from large federal procurement contracts.
The bilateral trade war is therefore not over. It has broadened beyond conventional tariffs and remains a direct risk to Canadian investment, exports and supply chains.
That makes the argument for diversification stronger, but it also makes financing decisions more complicated.
Companies considering a C$5 billion plant, mine, pipeline, port or data centre must make assumptions about demand, currency, tariffs, cross-border access, tax policy and regulation over decades. A trade conflict can motivate investment in alternative markets while simultaneously raising the cost and uncertainty of making those investments.
Canada's financial inflows illustrate that tension.
There has been exceptionally strong foreign demand for Canadian debt. Statistics Canada reported that non-resident investors added a record C$175 billion of Canadian debt securities in the first half of 2026, compared with only C$20.9 billion in the same period a year earlier.
Federal government debt accounted for a large share of that increase, while foreign investors also bought substantial amounts of private corporate bonds.
Those figures are meaningful. They show that international investors have been willing to finance Canadian governments and companies at very large scale during a period of global uncertainty.
But bond purchases are not the same as foreign direct investment.
Foreign direct investment generally reflects ownership stakes, acquisitions, reinvested earnings or capital committed to productive businesses. Portfolio purchases of debt securities can move much faster and may respond to interest rates, currency conditions, bond issuance patterns and short-term risk preferences.
On that measure, Canada's picture is more moderate than the 'capital flight from America to Canada' narrative suggests.
TD Economics reported that foreign direct investment into Canada totaled C$44.7 billion in the first half of 2026, down from C$54.7 billion during the same period of 2025.
U.S. direct investment remained strong at C$31.4 billion in the first half, making the United States again Canada's leading source of FDI. That is difficult to reconcile with claims that American capital is broadly abandoning Canada or that Canada has already replaced the United States with other investors.
The more accurate interpretation is that Canada is attracting record foreign demand in some financial markets while direct investment remains mixed.
There are also individual examples of manufacturers looking north because of trade conditions.
Some U.S. firms with international customer bases have discussed establishing or duplicating production in Canada to gain access to Canadian trade agreements and reduce exposure to U.S. trade policy. Wildlife Acoustics has described plans to add manufacturing capacity near Toronto, while Howell Ski Bindings has discussed future Canadian production.
Those examples are relevant signals, but they are not yet evidence of a mass relocation of American manufacturing.
Howell's own website says its first bindings are planned for shipment in 2029. That makes the company an example of planned future production rather than a mature factory that has already moved north.
This distinction between anecdote and macroeconomic trend runs throughout the investment debate.
Canada has clearly become more attractive for certain projects because it offers abundant resources, political stability, access to Europe and Asia through trade agreements, and a government determined to expand strategic industries.
But one or two corporate announcements cannot establish that global business investment has fundamentally shifted away from the United States.
The Carney government is trying to improve the odds through the Major Projects Office, created to coordinate federal reviews and help large projects move through regulatory and financing obstacles more quickly.
The office began with a smaller list of referred projects and strategies in 2025. By mid-2026, its public project page listed 18 projects and nine transformative strategies representing roughly C$192 billion in new investment, along with a stated potential to unlock hundreds of billions more in future private-sector investment.
That program is related to TD's investment-supercycle thesis, but it is not the same thing as TD's C$1 trillion project inventory.
The two numbers come from different exercises.
TD independently surveyed more than 300 publicly announced projects across five broad sectors. The Major Projects Office is a federal mechanism focused on a selected group of projects and strategies that require government coordination and are considered important to national economic or strategic objectives.
Combining the two into one headline can lead to double counting or the false impression that the federal government has approved every project in TD's list.
The government's broader investment targets also need careful handling.
Ottawa says its capital investments and incentives, totaling roughly C$280 billion over five years, are intended to enable more than C$1 trillion in total investment from public, private and institutional partners.
That C$1 trillion policy objective overlaps conceptually with the scale of the TD pipeline but is not the same statistic. It should not be added mechanically to TD's C$1 trillion as though Canada suddenly has C$2 trillion of separate committed projects.
The most subtle number in the debate is TD's C$1.5 trillion to C$1.7 trillion high-investment scenario.
The correct interpretation is more complicated than either side of the viral argument often suggests.
TD's report models a 'flywheel' scenario in which real non-residential investment grows about 7% per year over the next decade, far above its roughly 2% long-term baseline. Under that scenario, TD says cumulative nominal investment would be roughly C$1.5 trillion to C$1.7 trillion bigger over the next ten years than under its baseline path.
So the C$1.5-C$1.7 trillion figure is indeed an additional amount relative to the baseline scenario in TD's model.
But it is not a second, already identified list of C$1.5-C$1.7 trillion in committed projects stacked on top of the existing C$1 trillion pipeline.
It is a scenario result that assumes successful projects generate confidence, productivity, capacity and follow-on investment that has not yet been publicly announced.
That is why TD describes the mechanism as a flywheel effect.
If early projects are approved, financed and completed, private-sector confidence could improve. Better infrastructure could make later projects more viable. New electricity supply could attract data centres and factories. New mines could support processing facilities. New ports and rail could make additional export capacity economic.
That feedback loop is the essence of the supercycle thesis.
It is also where the greatest uncertainty lies.
Canada has struggled for years with weak business investment per worker, slow productivity growth, long approval timelines and infrastructure bottlenecks. TD itself says major policy changes are necessary if the country is to realize the upside case.
The bank highlights faster regulation, fewer interprovincial barriers, improved labour mobility, skilled-worker development and a more competitive tax environment as important conditions.
Those are not minor implementation details. They determine whether a proposal becomes a construction site and whether a construction site becomes a productive asset.
Indigenous participation is another central factor, particularly in energy, mining and infrastructure projects that cross traditional territories or require long-term local partnerships.
Successful projects increasingly depend not only on consultation but on equity participation, revenue sharing, procurement opportunities and durable agreements with First Nations, Inuit and Metis communities.
Execution risk also comes from capacity itself.
A true investment supercycle would create shortages as well as opportunities. Canada would need enough engineers, electricians, heavy-equipment operators, construction workers, project managers, specialized manufacturers and regulatory expertise to build many large projects at the same time.
Competition for labour and materials could raise costs, delay schedules and force projects to sequence construction rather than proceed simultaneously.
The energy system could become another bottleneck. Mines, data centres, factories and electrified transportation all require reliable power, while new generation and transmission projects can take years to approve and build.
That is why the Peace River nuclear proposal is both emblematic and cautionary. If a project of that scale is eventually built, it could materially expand power supply and support industrial growth. Today, however, it remains in a regulatory process rather than producing electricity.
Canada's diversification effort also faces a geographic reality.
Europe and Asia are much farther from Canadian factories and resource regions than the United States. Selling more energy, minerals, agriculture and manufactured goods to those markets requires ports, rail capacity, pipelines, export terminals, storage and trade finance.
The federal government's growing focus on trade corridors is therefore not peripheral to the investment strategy. It is a prerequisite for it.
Carney's government is now pushing that argument more aggressively as relations with Washington deteriorate.
The prime minister is seeking deeper economic ties with Europe and has argued that Canada should use the current crisis to build greater strategic autonomy. That does not mean replacing the United States as a trading partner. It means reducing the economic damage that any one government can inflict by controlling access to Canada's overwhelmingly largest export market.
The challenge is that diversification is usually measured in years, while tariffs can hit in days.
Canadian exporters are already dealing with higher barriers in the U.S. market. The government's response includes counter-tariffs and billions of dollars in support for affected workers and businesses, but those measures cannot immediately create new customers or new infrastructure.
That is why Carney has warned that the pivot will carry a cost.
The political argument over Canada's trillion-dollar pipeline will therefore turn on execution rather than announcements.
Supporters of the government's approach can point to an unusually large project pipeline, record foreign demand for Canadian debt, an expanding Major Projects Office and a clear strategic rationale for building more energy, defence, AI, mining and transportation capacity.
Critics can point to the large share of projects that remain proposed, Canada's long history of delayed infrastructure, moderate foreign direct investment, labour and regulatory constraints, and the possibility that trade conflict itself makes businesses more cautious.
Both sides are describing real parts of the picture.
The strongest factual conclusion is neither that Canada has already won an investment boom nor that the trillion-dollar figure is meaningless.
TD Economics really did identify more than 300 announced projects worth just over C$1 trillion. The pipeline really is broad enough to change Canada's investment trajectory if a substantial share is built. The government's project-acceleration strategy and the trade war have given the investment debate greater urgency.
But the pipeline is not equivalent to cash already spent, construction already underway or economic output already delivered.
Foreign investors are buying Canadian debt at record levels, but direct investment is not surging across the board. U.S. capital remains important. More than two thirds of Canada's exports still go to the United States in recent monthly data. The trade conflict has intensified rather than disappeared.
And the C$1.5-C$1.7 trillion upside scenario is a model of what could happen if an investment flywheel takes hold - not a second pile of committed projects waiting to be counted.
Canada therefore has something more interesting than a viral victory narrative.
It has a genuine opportunity under pressure.
The U.S. trade shock has made the costs of dependence harder to ignore. The project pipeline gives Canada a plausible route toward more diversified growth. The federal government is building institutions designed to speed major projects. Global investors have shown a strong appetite for Canadian debt, and new trade partnerships are moving higher on the national agenda.
Whether those ingredients become a true supercycle will be determined project by project.
The decisive numbers will not be the value of announcements. They will be final investment decisions, construction spending, completed transmission lines, producing mines, operating reactors, functioning data centres, expanded ports, export volumes and productivity gains.
That is the test facing Canada over the next decade.
The trillion-dollar pipeline is real.
The supercycle is still conditional.
May you like
And the trade war that helped make the opportunity urgent is far from over.